logo

Friday, April 2, 2010

NFP +162,000


From the BLS:

Nonfarm payroll employment increased by 162,000 in March, and the unemployment rate held at 9.7 percent, the U.S. Bureau of Labor Statistics reported today. Temporary help services and health care continued to add jobs over the month.
Employment in federal government also rose, reflecting the hiring of temporary
workers for Census 2010. Employment continued to decline in financial activi-
ties and in information.


First, let's remember there are two surveys -- the household and the establishment. The household provides information for the unemployment rate. So, let's start there.


It appears the unemployment rate has topped out in the 9.5%-10% range. While we're not seeing any downward momentum, we aren't seeing anymore strong upside moves either.

Also note the unemployment rate continues to be high for those with low educational achievement and low for those with high educational achievement:

Unemployment rate for

Less than a high school diploma: 14.5%
High school with no college: 10.8%
Some college or associates degree: 8.2%
Bachelor's or higher: 4.9% (this is near full employment from an economic perspective).

The civilian labor force increased by 398,000. This is a very important number because it is the denominator in the unemployment calculation. Last month we also saw an increase of 134,000 in overall unemployment. That means the unemployment rate remained stable at 9.7%.

The participation rate increased .1%, indicating more people are moving back into the civilian labor force.

Those "not in the labor force" decreased 238,000.

Those who were unemployed between 0 and 26 weeks decreased as well. The only time category that increased was the 27+ weeks unemployed.

Those working part time for economic reasons increased 263,000.

The establishment survey was solid. First, total private hiring was 123,000 -- meaning the "census workers tilted the numbers" argument is wrong. Secondly, goods producing jobs increased 41,000. This sector of the economy has been a drag on growth for the last few months. In addition, construction and manufacturing jobs account for the vast majority (over 70%) of all job losses during the recession. So an increase is welcome.

In addition, service jobs also saw an increase 82,000, with only two service sector areas (financial services and information technology) showing decreases.

While average hourly earnings decreased (largely because of labor market slack) weekly hours increased by .1 meaning weekly earnings increased from $762.41 to $763.98. The index of aggregate weekly hours increased from 91 to 91.4

Overall, this is a solid report.

Let me add this caveat. On August 22, 2009, I wrote the following:

Now -- that leads to the final question: when will the jobs come back? In order for that to happen we need to see at least one quarter of a positive GDP and probably two. That means the soonest we can expect a drop in the unemployment rate would be the a few months from now and that is only under the rosiest of scenarios. The most likely possibility is it won't be until the end of the first quarter of next year before we start to see a ticking down (and that assumes a stronger rate of growth than I think is going to happen).

Forex Fridays

Starting with the big picture, prices are in a clear uptrend, although they are approaching important technical support. The EMAs are in a bullish configuration, but the 10 and 20 day EMAs have recently turned lower. Prices are also below the 10 and 20 day EMA, which will pull prices lower going forward. The MACD is about to give a sell-signal. Also note the degree to which money has flowed out of the security (the A/D line at the bottom).


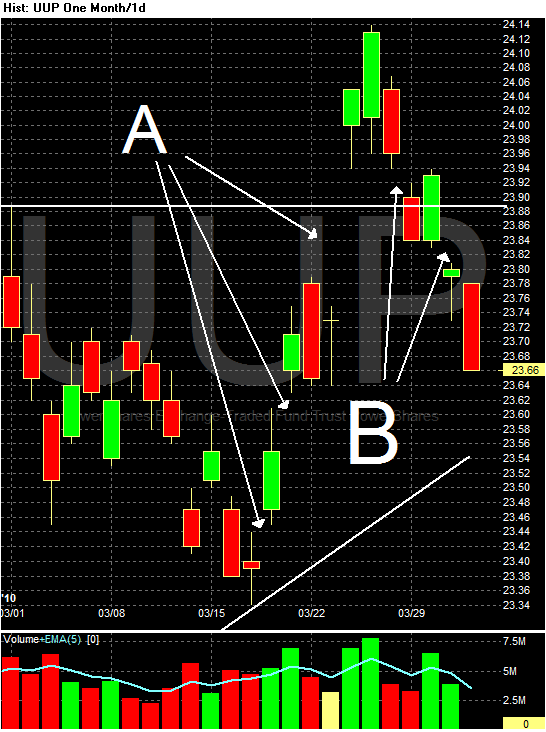
In the last few weeks we've had several large gaps higher (very bullish) and several gaps lower (bearish). The real question to ask about this chart is this: is the last gap higher an exhaustion gap -- the last hurrah of the bulls?


Last Wednesday we had a big gap higher (A) followed by an island reversal (B). Prices gapped lower for two days (C) and then gapped lower again (D). Note that prices are generally in a lower trending orientation right now.

Yesterday's Market


Consider the price action for the entire week.

A.) On Monday, prices gap higher, attempt a rally in the AM that fails and then spend the rest of the day trading sideways. Prices do move higher at the end, but can't get above highs set in the AM.

B.) On Tuesday, prices gap higher at the opening, attempt a rally but the rally quickly stalls. Prices close near the open.

C.) On Wednesday, prices gap lower in the AM, rally to around the opening price and stay there for most of the day until a late day sell-off puts prices back about where they started.

D.) Yesterday, prices gap higher at the open but can't hold the momentum. The fall until a late day day places prices near the open.

As a result of this action, you get the following daily chart:


Note the incredibly weak bars over the last few days.

In short, all week long we've seen an extraordinary lack of momentum in the market.

NFP +162,000


From the BLS:

Nonfarm payroll employment increased by 162,000 in March, and the unemployment rate held at 9.7 percent, the U.S. Bureau of Labor Statistics reported today. Temporary help services and health care continued to add jobs over the month.
Employment in federal government also rose, reflecting the hiring of temporary
workers for Census 2010. Employment continued to decline in financial activi-
ties and in information.


First, let's remember there are two surveys -- the household and the establishment. The household provides information for the unemployment rate. So, let's start there.


It appears the unemployment rate has topped out in the 9.5%-10% range. While we're not seeing any downward momentum, we aren't seeing anymore strong upside moves either.

Also note the unemployment rate continues to be high for those with low educational achievement and low for those with high educational achievement:

Unemployment rate for

Less than a high school diploma: 14.5%
High school with no college: 10.8%
Some college or associates degree: 8.2%
Bachelor's or higher: 4.9% (this is near full employment from an economic perspective).

The civilian labor force increased by 398,000. This is a very important number because it is the denominator in the unemployment calculation. Last month we also saw an increase of 134,000 in overall unemployment. That means the unemployment rate remained stable at 9.7%.

The participation rate increased .1%, indicating more people are moving back into the civilian labor force.

Those "not in the labor force" decreased 238,000.

Those who were unemployed between 0 and 26 weeks decreased as well. The only time category that increased was the 27+ weeks unemployed.

Those working part time for economic reasons increased 263,000.

The establishment survey was solid. First, total private hiring was 123,000 -- meaning the "census workers tilted the numbers" argument is wrong. Secondly, goods producing jobs increased 41,000. This sector of the economy has been a drag on growth for the last few months. In addition, construction and manufacturing jobs account for the vast majority (over 70%) of all job losses during the recession. So an increase is welcome.

In addition, service jobs also saw an increase 82,000, with only two service sector areas (financial services and information technology) showing decreases.

While average hourly earnings decreased (largely because of labor market slack) weekly hours increased by .1 meaning weekly earnings increased from $762.41 to $763.98. The index of aggregate weekly hours increased from 91 to 91.4

Overall, this is a solid report.

Thursday, April 1, 2010

Initial Unemployment Claims Drop

From Bloomberg:

Fewer Americans filed claims for jobless benefits last week, bringing the average over the past month to the lowest level since 2008, as the economic recovery prompted companies to retain staff.

Initial jobless applications declined by 6,000 to 439,000 in the week ended March 27, in line with the median forecast of economists surveyed by Bloomberg News, Labor Department figures showed today in Washington. The number of people receiving unemployment insurance was little changed, while those getting extended benefits rose.

Employers are slowing job cuts, a sign of confidence, as the U.S. emerges from the worst recession since the 1930s. Sustained employment gains are needed to boost consumer spending, which accounts for about 70 percent of the economy.

“We are turning a corner in the labor market,” said Julia Coronado, a senior U.S. economist at BNP Paribas in New York, who had forecast a decline in the weekly jobless claims. “Businesses are gradually starting to have more confidence in the recovery.”

.....

Employers announced fewer job cuts in March than a year earlier, another report showed today. Planned firings fell 55 percent last month to 67,611 from 150,411 a year earlier, according to data collected by the job placement firm Challenger, Gray & Christmas Inc. Announcements increased from February’s three-year low of 42,090.

Let's go to the data:


A few weeks ago, I expressed concern about the initial claims numbers, largely because they seemed to be unable to continue to move lower. Over the last several weeks we've seen those numbers drop a bit which eases my mind. However, a continued move lower to the 400,000 range is really needed right now.


The job cut number has been pretty low for awhile now and points to continued improvement in the jobs market.

State Tax Revenues & Withholding Taxes Increase

- by New Deal democrat

Most of my analysis proceeds from the view that leading indicators still lead, and lagging indicators still lag. While no approach is perfect, you will be right a lot more than most armchair (and highly-paid) pundits if you simply proceed from the premise that It Isn't Different This Time, and that while each recession, recovery, and expansion will have areas of variance from the norm (as in housing bubble and bust that still persists), in the main they will abide by past patterns. I parted from the vast majority of the doomish econoblogosphere almost a year ago when I noticed that consumers were refusing to play dead but, zombie-like, were rising from the grave to spend again, at least making a bottom in those figures. Shortly thereafter, the Leading Indicators almost all began to stabilize or even turn positive, in the face of the most severe economic downturn in decades.

As time has gone on, more and more of the bearish argument has focused on lagging indicators, and as an exercize to show that they do indeed lag and would turn positive in time, just as in prior recoveries, I have been tracking them here.

Most pointedly, back in November, Lee Adler of the Wall Street Examiner wrote a piece called Retail Sales Data, Tell me another Joke in which he said:

The reported rise in retail sales this morning had the media had in a full throated bull chorale...But as usual it’s all hype, little substance. A dead cat bounce is not a recovery. The “recovery” the pundits are talking about is little more than a semantic game. Bernanke sounds more like Chauncey Gardener every day. If this is recovery it must be just like the “recovery” that took place in the 4th quarter of 1929 and first quarter of 1930.
Adler's piece was quickly picked up by the usual suspects, as proof that the Recovery was illusory. Now, I respect Lee Adler a lot, and in particular he was one of few non-permabears who called the September-October 2008 crash ahead of time. But the fact is that state and withholding tax collections lag. You have to have the recovery and the hiring first, before people pay taxes on their new jobs and revenues!

This was an argument I had already had last July at the place where I used to blog, when they claimed that the worst state tax revenue declines in 46 years meant Doom was upon us. I pointed out in a comment that the bottom in revenues would come one or two quarters after the bottom in the economy, to no avail, because in January of this year, they did it again, claiming If this is a Recovery, shouldn't tax revenue be increasing?

Now we know that even before they were writing this, in the last quarter of 2009, according to an article in Business Week, state tax revenues were indeed beginning to increase, one to two quarters after the bottom in the economy, just like I said they would:

The two-year slide in tax collections that opened a $196 billion gap in U.S. state budgets has stopped, easing pressure on credit ratings and giving leeway to lawmakers as they craft spending plans for next year.

The 15 largest states by population forecast a 3.9 percent gain in tax revenue in fiscal 2011, budget documents show. The 50 states on average may increase collections by about 3.5 percent, the first time in two years the figure is expected to grow, said Mark Zandi, chief economist at Moody’s Economy.com,
....

Combined state and local tax collections climbed to $360.1 billion during the final three months of 2009 , the first year- over-year gain in five quarters and an almost 1 percent boost from the same period in 2008, according to the agency.
....

“We’ve seen the worst,” said Philip Condon, who oversees about $9.4 billion in municipal bonds for DWS Investments in Boston. “While it may not be great, it’s getting better.”
Although getting recent, accurate state tax receipt data on the internet is fiendishly difficult, it nevertheless appears that once again, Mish unintentionally bottom-ticked an economic indicator a month ago when he highlighted the shortfall in November 2009 state revenues.

Adler's piece noted that the reporting of state tax revenue (by the Rockefeller Institute) lagged badly, usually 4 months behind the collections. So he made use of the Daily Tax Receipts (h/t Matt Trovisonno) for more recent information, claiming that they too showed a non-Recovery. The TrimTabs mantra of poor withholding receipts comparisons had also been picked up by others of the Doomish persuasion. But of course those taxes too are lagging indicators, and as I've been noting weekly for the last few months, the YoY comparisons kept getting better and better until this month, they finally surpassed the taxes withheld in March 2009. As I write this, with one day left of reporting, March 2010 taxes withheld are already ahead of last year, $159.2B to $156.0B (and nearly equal to the March 2008 figure of $162.6B).

Well, TrimTabs will no longer give them comfort either, because as of yesterday they claim that the economy added between 80,000 and 130,000 non-Census jobs in March. [Note: I am not endorsing their analysis, which has been suspect in the past. The point is that in the parlance of sandlot baseball, "your own man says so."]

Leading indicators still lead, and lagging indicators still lag. It wasn't different this time. With their withholding, sales, and state revenue arguments gone or rapidly dissipating, there really is very little (bank loans, but historically those lag too) in the statistical data left for Doomsters to hold onto.

ISM Manufacturing Index Shows Further Strong Expansion

- by New Deal democrat

The ISM Manufacturing Report for March 2010 showed almost across the board increases. Only employment (at 55.1) and the backlog of orders (at 58.0) decreased slightly, meaning both increased, but at a slightly slower rate. Exports also increased at a faster rate, as did every other component of the index.

The overall index increased to 59.6, the highest since July 2004. Indeed, this is the strongest ISM number since the 1982 recession, with the exception of 9 months in 1984, 2 in 1987, and 8 in 2004. There is simply no doubt now that manufacturing is having a V-shaped recovery and is leading the way in the economy.

Here are the sample quotes provided by the ISM:
• "Certain markets served have increased by 50 percent in new customer orders, while other markets are not as strong." (Miscellaneous Manufacturing)
• "Business levels continue to be strong coming out of the Chinese New Year. First quarter will be our best since 2000." (Machinery)
• "Business is steady and prospects are good for Q2." (Food, Beverage & Tobacco Products)
• "After-market sales are improving as more vehicles require maintenance." (Transportation Equipment)
• "There is a serious shortage of basic electronic components, and lead times are becoming a problem. We are also seeing dramatic price increases." (Computer & Electronic Products)
As to employment, the ISM said:
This is the fourth consecutive month of growth in manufacturing employment. An Employment Index above 49.8 percent, over time, is generally consistent with an increase in the Bureau of Labor Statistics (BLS) data on manufacturing employment.
Although it would have been nicer had the employment index increased, showing faster growth, this is an almost perfect report, and its leading component adds to the likelihood that March's Index of Leading Indicators number will be quite good, meaning continued growth in the next 3-6 months.

From Bonddad

Here is a chart of the overall ISM reading:


This is not simply a one and done situation -- that is, we aren't just seeing one good number out of a series of bad numbers. This number has continued to rebound from low levels for some time -- as in over one year. The shows the underlying economy is strengthening and has been for some time.

In addition, consider this chart of the industrial sector:


Prices are in a strong uptrend (A) and the EMA picture is strong -- shorter EMAs are above longer, all EMAs are rising and prices are above all the EMAs. The two problems with this chart are the same problems that exist with the larger averages -- momentum is decreasing (C) and the money flowing into the security is slowing (D). The last two indicate we may be setting up for a correction in the near term.

Yesterday's Market

All of the charts below tell the same story: prices have broken important uptrends and the MACD is giving a sell-signal. This is the case with the big caps (SPYs), mid-caps (IWRs), small caps (IWMs), microcaps (IWC), and transports (IYT). In addition, over the last few weeks we've seen the leaders -- indexes that increased -- move from the smaller indexes (IWCS and IWMs) to the larger stocks. This indicates a move to more conservative investments.


Thursday Oil Market Round-Up


The oil market chart has been very perplexing for some time. Consider this yearly chart with simple price bars and nothing else:


There is just not a lot to sink you teeth into on that chart. In general, prices have moved between a few prices, but that's about all you can say. Ideally, we want to see prices move firmly in any direction. Instead, there has been a lot of zig-zagging between points.

That being said, let's look a little closer at the chart:


A.) For the last few weeks, prices have moved between two different price levels: 40.40 and 38.30.

B.) The EMA picture is turning bullish: the shorter EWAs are moving higher and the shorter EMAs are above the longer EMAs. But we've seen the EMAs bounce around the 200 day EMA for the last few months, advancing and then declining, only to advance again.

C.) Momentum is about to give a buy signal and

D.) Money is flowing into the stock.

Ideally the last two indicators tell us we're going to see a move higher, through some of the upside resistance areas. This would coincide with the "summer driving season."

No More Boom and Bust?

Those of you with long memories may recall some years ago the then Chancellor, Gordon Brown, boasting in parliament that there would be "no return to boom and bust".

However, politicians' promises are as fleeting as the early morning dew. Following on the from the worst recession in decades, the CIPS/Markit manufacturing purchasing managers' index (PMI) rose to 57.2 in March (from 56.5 in February). This is the highest level since October 1994.

Additionally, the Post Office is set to offer "super sized" mortgages to people with only a 10% deposit; thus hoping to end the loan drought that has held back the housing market.

However, those of you who fear a boom should take comfort in the fact that the TUC has promised months of industrial unrest. This will guarantee that any boom will be short lived, as the "brothers" seek to push the economy back into the economic doldrums.

In retrospect maybe Brown was right, there will be no return to boom and bust; we seem to be condemned to live in a permanent state of "bust".

Share

Twitter Delicious Facebook Digg Stumbleupon Favorites More